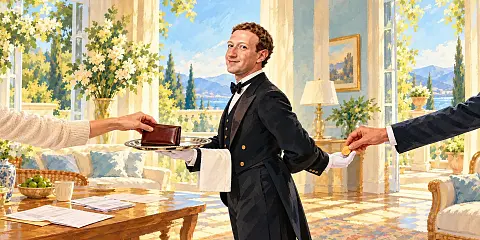
Would you hand your wallet to Zuckerberg?
September 29, 2026
Sunday afternoon. On the table: bank and credit card statements, the electricity bill that has gone up again without anyone knowing why, a car insurance renewal that renewed itself, and the vague impression that we are still paying for a streaming platform we haven't used since the pandemic. Faced with the mess, you decide that calling your internet provider to fight over the rate requires forty minutes of hold music and the inner balance of a Buddhist monk. So you push the bitterness on to next Sunday. And maybe the one after that.
It's not a tragedy, but you get the feeling that your checking account is under siege from angles you don't even suspect. And the account doesn't refill itself; it refills with hours of work that go down the drain.
In June, in this very series, I wondered whether the killer app of generative AI would arrive in time. I concluded that it wouldn't be a smarter chatbot, but something everyday, built around a model, that solved real problems people have every day. Something that would keep my mother from giving up on it. Three months later, Mark Zuckerberg took the stage at "Meta Connect" with a candidate under his arm. And, like almost everything that comes out of his company, it arrives full of fine print.
From geek toy to everyone's tool
It's called Muse, it launched in the US on September 8, and within a few days it shot to the top of the Apple and Google app stores. It's not a chatbot, but a general-purpose agent for everyone. Something that reads your email and your calendar, books appointments, organizes plans, calls customer service for you, handles returns, appeals fines, cancels forgotten subscriptions and buys on your behalf. And that's not all. If you're American, it will also shop at Walmart, Best Buy or Sephora, book trips on Expedia and do your grocery shopping through Instacart. Soon it will have its own email address and an avatar you can talk to over video call.
The geeks around me will say that none of this is technically new. And it's true: they, who have been tinkering for months with agents like OpenClaw, know what one of these critters can do with access to your computer. Meta's own head of AI said as much at the launch: six months ago, having a personal agent running on your computer was the province of a small group of crazies. What's new is that Meta has packaged it so anyone can use it, with a customizable mascot and no need to know what a terminal is.
Zuckerberg has named his own Agrippa, complete with toga and laurel wreath. Ego stuff, I suppose. But the historical parallel is a little unnerving: Agrippa was the right-hand man of Augustus (the first Roman emperor), who was formed in Caesar's circle (Peter Thiel?). Food for conspiracy theorists.
We have to acknowledge something that in Europe we tend to dismiss with a grimace, but that Americans take very seriously: the value proposition is formidable.
Eight minutes that weigh like eight hours
Muse's value doesn't lie in any of its functions individually, but in the sum: freeing you from the hassle of administering your daily life. That domestic bureaucracy we all suffer: appointments, bills, complaints, renewals, passwords, forms. In Germany, a study published in 2024 put it at about seven hours a month per person. And a good part of it revolves around money.
In the United States there is a tradition that is only now starting to take root in Spain: personal finance software. Intuit was born in 1983 from a scene similar to the one that opened this article: Scott Cook, its founder, watching his wife wrestle with the family checkbook at the kitchen table on a Sunday afternoon. Then came Microsoft Money, Mint, and a few more. Here we have Fintonic and the banks' dashboards, but not so much the culture of sitting down in front of an app to balance the household budget.
What problem do these apps solve for millions of Americans? The intuitive answer is "time," but that's not quite right.
A study published this year in the Journal of Behavioral and Experimental Finance measured it using the official American Time Use Survey. Americans spend on average a mere 8.3 minutes a day managing their finances. Not much, but they are among the most stressful and least happy minutes of the day's activities. More stressful, for example, than doing housework.
What is lost is not time. It's peace of mind. It's the mental load of knowing there is something pending, that you are probably being overcharged, or that you should check that odd charge. Anyone past forty, with children, elderly parents, a second home or a somewhat complicated life, knows exactly what I'm talking about.
And if that happens with money, the best-measured part, there's no reason to think the rest of domestic bureaucracy weighs any less. How long did you put off your last doctor's visit just to avoid opening the relevant app or picking up the phone to fight with an answering machine? Well, that's why an agent that takes all of that off your hands is not a gadget, but a contender for the killer app we were looking for. A powerful proposition for consumers with more complex lives and more purchasing power. So powerful that many will be willing to forget who is offering it.
Dangerous liaisons
Because it's Meta offering it. The Meta of the Cambridge Analytica scandal. The Meta of the FTC's record $5 billion fine in 2019 over its handling of privacy. The one that built one of the most profitable businesses in history by knowing more about you than your mother does. And that is now asking for access to your apps, your email, your accounts and your credit card.
Zuckerberg knows his reputation better than anyone, and has bandaged the wound before the stone is even thrown. He has done so by presenting a secure credential vault so the agent can't read your passwords or your cards, a secure virtual machine where your information lives and, soon, a "confidential" version in which not even Meta will be able to see your data.
Those of us more aware of these issues may smile skeptically. But history suggests it doesn't matter. Researchers have been talking about the privacy paradox for years: we say we care a lot, but we act as if we didn't. Facebook kept adding users after Cambridge Analytica. And if people forgave that in exchange for seeing photos of their nephews and nieces, what won't they forgive in exchange for never fighting with their electricity company again? Can you imagine how it must feel to sic a tireless agent on every one of the customer service numbers that have exhausted your patience over the last few years?
The curious thing is that, in this case, privacy may not even be the relevant problem.
The butler was always a suspect
Muse does many things, and it gets paid in two ways. A subscription of $20 or $100 a month for heavy users, and another that Zuckerberg explained bluntly: Muse will be free for an enormous number of tokens, with the expectation that, over time, Meta will profit by charging a small commission on transactions.
On your transactions. Nobody is hiding anything here.
American personal finance companies have already tried out two opposite business models. Rocket Money negotiates your bills and charges between 35% and 60% of what it saves you in the first year, only if it succeeds. If it doesn't save you anything, it doesn't charge. Its incentive is yours: that you pay less.
Mint, on the other hand, was free. For years it was the go-to app in millions of American households. It lived, by its own account, on "a small commission from advertisers on some offers": credit cards, loans, insurance. Its incentive was not for you to sign up for more, but for you to do so with whoever was paying it. Between the card that suited you best and the one that left it the biggest commission, nothing obliged Mint to recommend the former.
And one would like to tell a fable here with a moral, saying that Intuit shut down Mint in March 2024 because the model failed. It would be a nice fable, but a false one. Mint didn't die because of its business model, but by decision of Intuit, which moved its users to Credit Karma, another of its companies, which lives off exactly the same model. Credit Karma brought in $2.6 billion in its last fiscal year, 20% more than the year before. It is the fastest-growing part of the group.
So we are left without a moral. Rocket Money, the model in which the user wins when they save, generates trust and is, according to industry estimates, the most-used personal finance app in the country. But Mint's heir, the model in which the provider wins when the user signs up with its partners, generates money. A lot of money.
This is not a theoretical conflict of interest. In 2022, the Federal Trade Commission forced Credit Karma to pay $3 million for telling its users they were "pre-approved" for credit cards that, in some offers, were then denied to almost one in three applicants. But every application earned it a commission. Such is life.
Muse has chosen the second model. And, as a butler who gets paid on the purchases he makes in your name, it adds up two incentives: that you buy, and that you buy where he gets paid. Meta hasn't clarified who will pay that commission, you or the store. Nor whether merchants will be able to pay to appear first when you ask the agent to find you something. If the store pays the commission, the conflict is Mint's.
Zuckerberg sold it clearly on stage: "We believe Muse will make you money." The best of both worlds: it's the Rocket Money pitch laid on top of the Credit Karma model. And it will probably work. Al Ries and Jack Trout put it in writing in 1993, in the fourth of their 22 Immutable Laws of Marketing, with absolute cruelty: "Marketing is not a battle of products, it's a battle of perceptions." What will decide Muse's success is not whom the agent works for, but whom we believe it works for.
With advertising, the risk we took on with Meta was limited to its possible indiscretion in handling what it knew about us. An abstract, diffuse risk, easy to ignore on a Sunday afternoon. With an agent that holds your card and acts on your behalf, the risk is one of loyalty: whom it works for when it buys for me. And that risk isn't abstract; it's itemized. On your bank statement, to be precise.
Paradoxically, the "confidential virtual machine" fits this model perfectly. The advertising business needed your data. The toll business doesn't. It's enough that you go through the checkout. Meta can afford not to look. It no longer needs to. Or so says the leopard: that this time it will change its spots.
The walled gardens are back
There's one last detail that is far from minor. Amazon has blocked Muse from shopping in its store. Anyone who tries gets a curt warning: continued access by an unauthorized AI agent violates its terms of use.
There's another curious story here. In November of last year, Amazon sued Perplexity for allowing the agent in its Comet browser to shop on its platform. In March, a California judge sided with Amazon and issued a preliminary injunction blocking access. But in August an appeals court overturned that injunction with a devastating argument: whoever accesses Amazon's computers is not Perplexity, but the user, who is assisted by an agent. In September, the court declined to review its decision. The lawsuit goes on, but Amazon has lost an important battle. A few days later, it blocked Muse. We'll see what happens with that fence.
Because there's a nuance that doesn't play in the favor of Bezos's people: Amazon's own shopping agent, Buy for Me, buys on other merchants' websites without having asked their permission. If they don't want it, they have to email to ask to be taken off. What Amazon demands of others in its own house, it doesn't practice in anyone else's.
But the risk for them is enormous. If agents become the new gateway to purchase intent, whoever controls the catalog loses the relationship with the customer. It stops being a store and becomes a warehouse with a counter staffed by someone else. Amazon has spent twenty years building exactly the opposite, and it's not going to hand it to Zuckerberg on a silver platter.
I lived through this movie in the early 2000s. At Terra, we were fighting Yahoo and MSN to be the browser home page of every user. The door through which people entered the Internet. Whoever controlled the door thought they controlled the business. And when we saw that Google's simplicity was endangering the future of portals, we started working on an idea from the great Jaime de Yraolagoitia, which we called "the Terra control center": a program (back then they weren't called apps) where users could conveniently group all the services essential to them. Something remotely similar to what we now call an "agent." Portal or agent, the name hardly matters, but the fight over the toll is the same. And, as back then, users will end up seeing only the part of the Internet that the owners of the doors have agreed on among themselves.
If we look at the other half of the Internet, China has reached the same place by the opposite route. WeChat has been the app for everything for more than a decade: messaging, payments, taxis, bookings, paperwork, through millions of mini-programs that live inside it. It has more than 1.4 billion users, and payments and financial services already account for almost a third of its owner's revenue. This summer, according to the trade press, WeChat began testing its own agent. You ask it to book a table, call a taxi or buy some tickets, and it goes through the mini-programs of Meituan, Ctrip or Didi and pays with WeChat Pay. You just confirm on your phone.
The difference lies in the order of the factors. WeChat built the garden first and is now adding a butler. The merchants were already inside, and the walls were raised by WeChat itself against its rivals, until in 2021 the Chinese regulator forced it to stop blocking links from Alibaba or ByteDance. Meta is doing exactly the opposite: it has the butler and is going out to find him a garden, signing deals with Walmart or Expedia while Amazon shuts the gate on it. Two halves of the Internet that have turned their backs on each other for twenty years are converging on the same business model: whoever controls the agent collects the toll.
Peace of mind can't be delegated on commission
Back to Sunday afternoon.
Muse's promise is to lift that burden off us: the statements, the bills, the calls, the constant suspicion that someone is overcharging us. It is a legitimate promise and probably the first application of generative AI agents that an ordinary citizen would understand without needing it explained. If someone delivers on it, they will have found the killer app.
But there is a contradiction that no virtual machine can resolve. A butler who has to be watched doesn't lighten our minds. We will have traded the anxiety of bills for suspicion of our own agent. Did it buy this because I needed it or because Meta gets a cut? Did it choose this flight because it was the best or because it was the partner's? Did it negotiate the rate I need, or did it renew it with an add-on?
The privacy paradox tells us that most people won't ask themselves these questions. That they'll accept the deal with the same cheerfulness with which they accepted the last one. That's probably how it will go.
The question is whether you can delegate your peace of mind to someone who gets paid every time you spend.
And you, would you hand your wallet to Zuckerberg?
This article is part of a series that began with "Less Wood, It's War!", and continues with "The end of the token open bar, or something more serious?", "What if the Genesis Mission were a huge mistake?", "Where's the pea?", "From packet to token, and back to square one", "Investing in typewriters", "Will the "killer app" arrive in time?", "Are they making room for us?", "Spot the 8 differences", "Will AI end up in a backpack?", "Will Nvidia be the new Kodak?", "Is CUDA Nvidia's magic potion?", "Neither conscience nor consciousness", "Neither Hawking nor Einstein. The true origin of intelligence", "Yogurts and tokens: welcome to the AI confusopoly", "The mathematician who left mathematics. What will we leave behind?", "How high is your fence?", "Will the new Encyclopedia be European?", "Find "digital transformation" and replace with "AI"?", "It's always day one". To be continued...
Our latest news
Interested in learning more about how we are constantly adapting to the new digital frontier?
Corporate news
October 7, 2026
Sngular grew by 7.2 per cent in the first half of 2026
Insight
September 17, 2026
The Role of Junior Professionals in the Age of AI: Perspectives, Challenges, and the Future of Talent in the Tech Industry